
Should You Put Money Down on a VA Loan If You Have It?
When you hear “zero down,” it’s easy to think: why would I put money down? The VA loan program gives active-duty military families an amazing benefit—homeownership with no down payment required. But what if you have the cash saved? Should you use it, or hold onto it?
Let’s walk through the options with a bit of financial strategy in mind.
Why VA Loans Work Without a Down Payment
The VA guarantees 25% payment of your loan in the event of a default. That protects the lender and helps you skip the down payment and private mortgage insurance (PMI).
But just because you can skip the down payment doesn’t mean you always should.
The Benefits of Putting Money Down on a VA Loan
Putting even 5% down can lower your monthly payment in two ways:
- Smaller loan = smaller payment
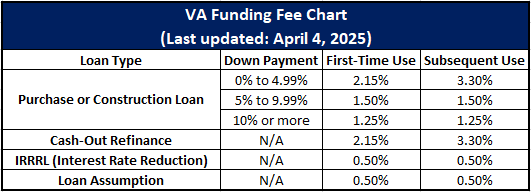
- Lower VA funding fee
- Less Interest Paid
But before you decide how much to put down on your VA loan, it helps to understand how that choice affects your VA funding fee—one of the biggest upfront costs tied to your loan.
When Does It Make Sense to Use a Down Payment?
You might be wondering: “Wouldn’t I get a better return keeping that money in the stock market?”
Here’s a quick way to think about it.
Say you’re buying a $500,000 home with a VA loan and you’ve saved $25,000. You could either put it toward the house or keep it in a brokerage account.
Put it down, and your loan drops to $475,000. That trims your mortgage payment by about $157 a month, reduces your VA funding fee by over $3,625, and cuts your first-year interest by roughly $1,600. Altogether, you save close to $7,109 in year one. That’s a total return on investment of about 28.4% on your $25,000.
Keep it in the market, and you might earn 8–12%—around $2,000 to $3,000 if it’s a good year. But that return isn’t guaranteed, and meanwhile, you’re paying interest on the full $500K loan. You’ll spend more each month and more over time.
Lower Payments, More Exit Flexibility
Military families know that no duty station lasts forever. Even if you buy with plans to stay for two to three years, orders can change that timeline fast. That’s why lower monthly payments don’t just feel good now—they give you more options when it’s time to move.
Here’s how:
1. Easier to Cash Flow as a Rental
If you decide to keep the home and rent it out, a lower mortgage makes that math work more easily. Rent doesn’t have to cover a high monthly payment just to break even. That cushion makes it more likely your rental produces income—or at least doesn’t cost you money during vacancy or turnover.
2. More Pricing Power If You Need to Sell
In a softer market or a quick-turn PCS, having a smaller mortgage balance gives you wiggle room. You won’t feel locked into a certain price just to cover your loan. That flexibility can help you move faster and avoid paying out of pocket to cover any closing costs.
Final Thoughts: Use Your VA Loan Flexibility Wisely
Your VA loan benefit gives you options most buyers never get. No down payment. No private mortgage insurance. Competitive interest rates. But just because you can skip the down payment does not always mean that you should.
Using savings toward a down payment can create meaningful advantages. It reduces the size of the loan, lowers the monthly payment, decreases interest over time, and brings down the VA funding fee. This creates a smoother and more affordable path forward from the start.
A lower monthly payment can also support future plans. When it is time to move, the home may be easier to rent. Selling may feel more manageable. You may experience less financial strain during the transition. Flexibility becomes part of your overall plan.
Each household brings its own set of goals and preferences. Some buyers focus on stability. Others value the ability to plan ahead. All benefit from understanding how the VA loan works and how their decisions shape future options.
You’ve got options. Let’s use them well.
Additional Resources
Frequently Asked Questions
Do you have to put money down on a VA loan?
No, the VA guarantees 25 percent of your loan to the lender, which lets you skip the down payment and private mortgage insurance entirely. That said, just because you can put zero down doesn’t mean you always should if you have cash saved up.
How does a down payment affect your VA funding fee?
Putting money down, even just 5 percent, lowers your VA funding fee in addition to shrinking your loan balance and monthly payment. The exact savings depend on how much you put down and whether it’s your first time using the benefit.
How much can putting $25,000 down on a $500,000 VA loan actually save you?
On a $500,000 home, putting $25,000 down drops your loan to $475,000, trims your monthly payment by about $157, cuts your VA funding fee by over $3,625, and reduces your first-year interest by roughly $1,600. Altogether that’s close to $7,109 in savings in year one, a return of about 28.4 percent on that $25,000.
Is it better to put money down or keep it invested in the market?
Keeping the money in a brokerage account might earn 8 to 12 percent in a good year, around $2,000 to $3,000, but that return isn’t guaranteed and you’re still paying interest on the full loan balance in the meantime. Putting it toward the home instead delivers a more certain, immediate return through a lower payment, lower funding fee, and less interest paid.
How do lower mortgage payments help with military PCS moves?
A smaller mortgage makes it easier to cash flow the home as a rental since rent doesn’t have to cover as high a payment just to break even. It also gives you more pricing flexibility if you need to sell quickly in a softer market, since you’re not locked into a certain price just to cover the loan.